Measure contribution by channel before you promote the next order
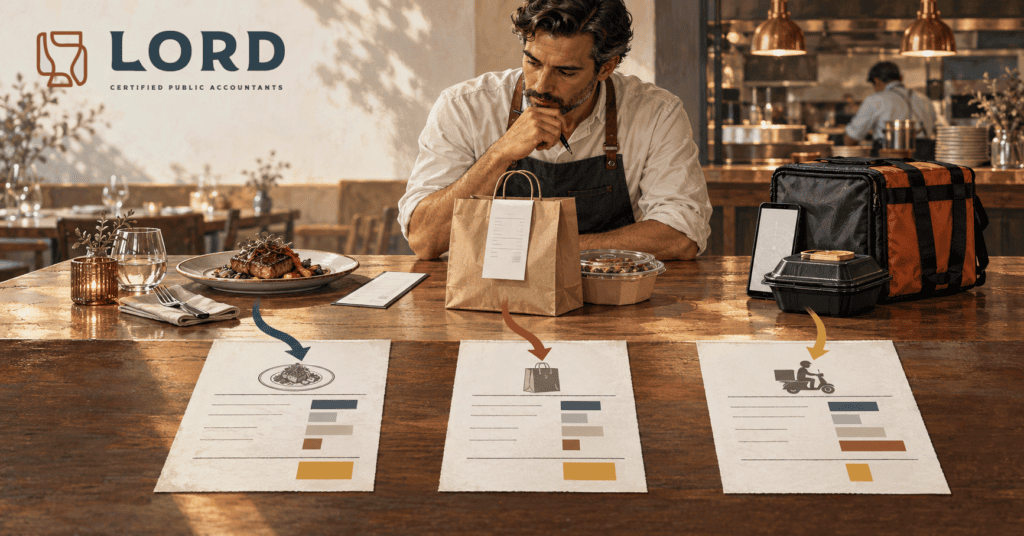
A delivery order can look exactly like a dining-room order on the top line.
Both may add $50 to sales. Both may move through the same kitchen. Both may appear in the same daily revenue report.
But they do not necessarily create the same economic result.
One order may require table capacity and front-of-house labor. Another may add packaging, ordering technology, and delivery expense. A marketplace order may also carry commissions, promotions, refunds, and settlement adjustments before the cash reaches the bank.
The sales number is real. It is simply incomplete.
In an October 8 report, MarginEdge said delivery represented 13.21% of nationwide restaurant sales in its September 2026 observed data. That figure is useful as a signal, not a universal benchmark: it reflects restaurants and transactions visible in MarginEdge’s platform data rather than every restaurant in the country.
The management question is therefore not whether delivery is large enough to matter. For many operators, it already is.
The question is whether the channel creates enough contribution to justify the costs, capacity, and complexity required to serve it.
Sales by channel are not economically neutral
Revenue is usually summarized as one amount on the profit-and-loss statement. That is appropriate for financial reporting, but it can conceal important operating differences.
A dining-room order, direct pickup order, first-party delivery order, and marketplace delivery order may consume different combinations of:
- Food and beverage product
- Packaging and disposables
- Credit-card and ordering fees
- Marketplace commissions and sponsored-placement costs
- Discounts, promotions, refunds, and chargebacks
- Kitchen, expediting, packing, and handoff labor
- Dining-room, curbside, or driver capacity
- Management attention and exception handling
- Guest data, loyalty, and the future relationship with the customer
The same amount of gross sales can therefore produce very different contribution.
That does not make marketplace delivery automatically bad, or dine-in automatically superior. A marketplace may create demand the restaurant would not otherwise reach. A direct channel may preserve more customer information and economics but require marketing, technology, and fulfillment capabilities the operator must fund. Dine-in may create beverage attachment and hospitality opportunities while consuming scarce seats at peak periods.
The useful question is not which channel is best in the abstract.
It is which channel creates the healthiest result for this restaurant, during this daypart, with this menu and this capacity.
Begin with contribution, not allocated profit
A channel analysis becomes confusing when every cost in the business is assigned to every order before management has answered a simpler question:
After the sale occurs, how much remains after the costs that change with or are directly attributable to that channel?
A practical starting point is:
Channel contribution = Net channel sales – Product cost – Channel costs – Incremental fulfillment cost
Net channel sales should begin after restaurant-funded discounts and refunds. Product cost should reflect the actual item mix, not simply the restaurant’s blended food-cost percentage. Channel costs may include commissions, payment processing, ordering technology, sponsored promotions, delivery charges paid by the restaurant, packaging, and channel-specific guest recovery.
Incremental fulfillment cost requires judgment. Some labor changes with every order. Some labor is scheduled for the shift and does not disappear merely because one channel slows down. Some orders use otherwise idle kitchen capacity. Others arrive during a constrained period and displace more valuable business or damage service across every channel.
This is why contribution is not the same as full restaurant profit.
Contribution asks whether a channel helps cover shared costs after its own economic burden. Full profit must also support management, occupancy, insurance, utilities, equipment, technology, and the rest of the operating system.
Both views matter. They answer different questions.
A hypothetical 100 dollars of sales
The following example is illustrative. It is not a benchmark and should not be used in place of the restaurant’s contracts, menu mix, labor model, and operating data.
| Per $100 of gross menu sales | Dine-in | Direct delivery | Marketplace delivery |
|---|---|---|---|
| Gross menu sales | $100 | $100 | $100 |
| Restaurant discounts and refunds | ($2) | ($3) | ($5) |
| Net sales | $98 | $97 | $95 |
| Food and beverage cost | ($29) | ($29) | ($29) |
| Channel, platform, delivery, and payment costs | ($3) | ($10) | ($25) |
| Packaging and disposables | ($1) | ($4) | ($4) |
| Incremental fulfillment labor | ($12) | ($10) | ($10) |
| Contribution before shared fixed costs | $53 | $44 | $27 |
A restaurant could look at this example and conclude that marketplace delivery should be eliminated.
That conclusion would be premature.
The marketplace may be reaching guests the restaurant would not otherwise serve. The orders may arrive during periods when the kitchen has usable capacity. Marketplace sales may introduce customers who later order directly or visit in person. The restaurant may be able to redesign the delivery menu, price certain items differently where permitted, reduce packaging cost, improve order accuracy, or change its platform plan.
The analysis does not make the decision.
It shows management which questions are worth asking.
Do not assume every labor dollar is variable
Labor is one of the easiest places to overstate or understate channel economics.
If the restaurant has a cook, manager, and expeditor scheduled regardless of whether ten delivery orders arrive, allocating a full share of those wages to each delivery order may make the channel appear less attractive than the near-term decision actually is.
But excluding labor entirely is equally misleading.
Delivery can require additional prep, packaging, order monitoring, driver handoff, remake activity, and guest recovery. At sufficient volume, the restaurant may need another position or more scheduled hours. During peak periods, channel demand may lengthen ticket times or consume capacity that could have served dining-room guests.
A better analysis separates three layers:
- Order-variable labor: time that reliably increases as order volume increases, such as packing or a dedicated delivery driver paid per delivery.
- Step costs: labor that changes only after volume crosses a threshold, such as adding an expeditor for the Friday dinner shift.
- Committed labor and capacity: people and resources already scheduled that may absorb additional volume until the operation becomes constrained.
The contribution model should show these distinctions instead of pretending every labor dollar behaves the same way.
Reconcile the channel from order to cash
A profitable-looking channel can still create accounting confusion if the restaurant cannot reconcile its orders to settlements and the bank.
A useful channel reconciliation follows the economic flow:
Gross orders -> discounts and refunds -> net sales -> taxes and tips -> platform fees and adjustments -> expected settlement -> bank deposit
Sales tax collected from the guest is generally a liability, not restaurant revenue. Tips held for employees are also not sales. Marketplace-facilitator rules, platform contracts, and local law may determine whether a platform collects or remits particular taxes. The accounting should reflect what actually happened rather than forcing every channel into one generic journal entry.
Timing matters too. Orders at the end of the week or month may not settle until the next period. Refunds and adjustments may appear in a later payout. A bank deposit is therefore not the sales number; it is the result of sales, liabilities, fees, adjustments, and timing.
When the POS, marketplace statement, accounting system, and bank deposit do not agree, management needs a repeatable reconciliation rather than an unexplained clearing-account balance.
Build a weekly channel scorecard
A restaurant does not need a fifty-column dashboard. It needs a small set of measures that explain whether each channel is economically healthy and operationally manageable.
- Orders and net sales by channel
- Average order value by channel
- Product cost based on actual channel mix
- Effective platform, delivery, payment, and promotion cost
- Packaging cost per order
- Refund, remake, chargeback, and cancellation rate
- Incremental labor hours or orders per fulfillment labor hour
- Contribution dollars and contribution per order
- Peak-period ticket time, order accuracy, and capacity signals
- Expected settlement compared with actual cash received
The scorecard should be reviewed at the frequency of the decision. A restaurant metric tree can connect those measures to the decisions they support.
Menu availability, delivery throttling, order accuracy, and peak-period capacity may need daily attention. Contribution by channel may be reviewed weekly. Contract terms and platform strategy may belong in a monthly or quarterly review.
The objective is to see the result while there is still time to change the operating conditions that create it.
Use contribution to make specific decisions
Once channel economics are visible, the restaurant can make decisions more thoughtfully.
- Keep a channel but narrow its delivery radius or operating hours.
- Throttle marketplace orders during periods when the kitchen or dining room is constrained.
- Create a delivery menu that travels well and produces enough contribution.
- Remove items that generate frequent refunds, remakes, poor quality, or weak margin off premises.
- Review restaurant-funded promotions separately from platform-funded incentives.
- Compare platform plans and negotiated terms using the effective total cost, not only the headline commission.
- Invest in direct ordering when the guest relationship, repeat demand, and unit economics support the cost of building that channel.
- Protect a lower-contribution channel when it fills otherwise unused capacity or serves a deliberate strategic purpose.
A channel does not need the highest percentage contribution to be valuable. It needs a clear role, economics the business understands, and operating guardrails that keep the channel from weakening the rest of the restaurant.
The channel is part of the operating system
Delivery is often discussed as a marketing decision: turn the platform on, gain access to demand, and grow sales.
But the financial result is created by much more than demand.
It is created by menu design, pricing, product mix, discounts, packaging, labor, kitchen capacity, handoff procedures, order accuracy, guest recovery, platform terms, accounting definitions, tax treatment, and settlement controls.
That makes delivery a financial and operating system.
The P&L may show sales and fees in separate accounts. The bank may show only the net deposit. Neither one, by itself, explains whether the channel is strengthening the business.
Management has to reconnect the order, the work, the contribution, and the cash.
At Lord CPAs, we help restaurant and hospitality leaders align POS, platform, and accounting information; understand the economics beneath channel sales; and build reporting that supports better operating decisions. If your sales are growing while margin or cash remains difficult to explain, a Financial Clarity Review can help identify where the financial story and the operating reality have separated.
