Automatic gratuity sounds like a tip. In the POS, it may even sit beside the tip button. But for federal tax and wage purposes, a mandatory charge generally is a service charge, not a tip.
That distinction changes what happens next. A voluntary tip can flow through tip reporting. A mandatory service charge is income to the restaurant; when the restaurant distributes it to an employee, the payment is generally treated as wages. That affects payroll withholding, Form W-2 reporting, overtime calculations, the FICA tip credit, Form 8027, and the way managers read labor and margin reports.
The operational problem is rarely a single bad journal entry. It is a chain of mismatched definitions. The menu calls the amount a gratuity. The POS maps it to tips payable. Payroll treats it as reported tips. Accounting nets it against sales. The employee sees a line on the pay stub that nobody can explain. Each system can look internally consistent while the full transaction is wrong.
Year-end is the right time to fix the chain. The goal is not a new spreadsheet. It is one clear classification that survives every handoff from the customer’s bill to payroll and the general ledger.
Start with the facts, not the label
The IRS looks at whether the customer controls the payment. Current IRS guidance says a payment is generally a tip when it is made free from compulsion, the customer can determine the amount (including zero), the amount is not negotiated or dictated by employer policy, and the customer generally can determine who receives it. If those facts are missing, the payment may be a service charge.
That means an 18% amount added automatically to a large-party check is generally a service charge even if the receipt calls it a gratuity. A required charge in a banquet contract is generally a service charge. A payment prompt that will not let a guest complete the transaction without choosing an amount greater than zero can also be a service charge.
By contrast, suggested tip percentages can still produce a voluntary tip when the guest may enter any amount or leave the line blank. If a restaurant adds a mandatory charge and the guest voluntarily adds another amount, the transaction can contain both: a service charge and a tip.
The practical rule is simple: do not let the POS label make the decision. Document the policy, customer choice, and transaction design first. Then configure the systems to match.
Why 2026 reporting makes the distinction more visible
The 2026 General Instructions for Forms W-2 and W-3 add code TP in box 12 for total cash tips reported to the employer and box 14b for Treasury Tipped Occupation Codes. The instructions also say mandatory service charges are not qualified tips.
The extra reporting detail creates a useful control question: if payroll is going to report tips more specifically, can the restaurant prove that the amounts in the tip fields were actually voluntary tips?
The answer should not depend on a manager’s memory. It should come from a documented mapping between the POS transaction code and the payroll earning code. A restaurant that sends service charges into the same payroll bucket as reported tips may create incorrect Forms W-2, unreliable Form 8027 data, and inaccurate employee expectations about tip treatment.
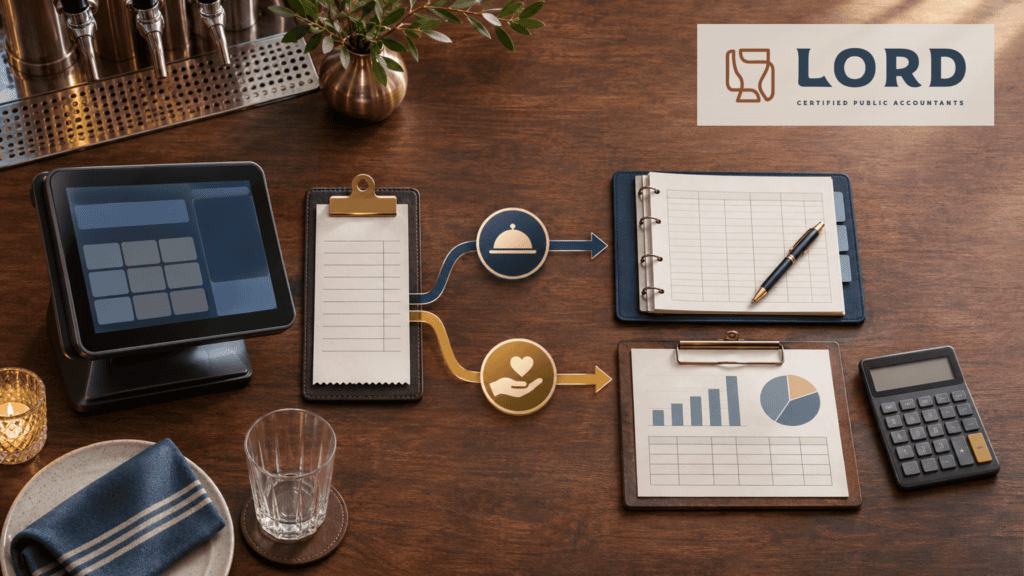
Follow one transaction through the entire system
Consider a hypothetical private event with these amounts:
- Food and beverage sales: $1,000
- Mandatory 20% service charge: $200
- Additional amount entered voluntarily by the guest: $50
For federal purposes, the $200 mandatory charge is generally income to the restaurant. If the restaurant distributes some or all of it to employees, the distributed amount is generally wages subject to withholding and payroll tax. It is not reported as tip income on Form 8027, and employer FICA taxes on that distributed service charge are not eligible for the section 45B FICA tip credit.
The extra $50 may be a tip if the guest could choose any amount, including zero, and the other tip factors are present.
This example is deliberately narrow. It does not decide state or local sales-tax treatment, service-charge disclosure rules, tip-pool restrictions, or wage-and-hour requirements. Those rules vary. The point is to show that one guest check can contain three different economic streams: sales, a mandatory charge, and a voluntary tip. Combining them in one POS code makes every downstream report harder to trust.
Build one data dictionary across the restaurant
A clean operating definition should answer the same questions in every system:
- What did the guest control? Could the guest reduce the amount to zero without manager intervention?
- What did the restaurant require? Was the charge set by policy, menu language, event contract, or POS design?
- Who owns the amount first? A mandatory service charge is employer income even when the operator plans to distribute it to employees.
- How will it be paid to employees? Map distributed service charges to a wage earning code, not to the employee-reported tip code.
- How will it appear in management reporting? Show mandatory charges, service-charge wages, and voluntary tips separately so managers can see the true economics.
This is the same discipline that makes restaurant AI useful: definitions have to be reliable before the output can be trusted. If the operating systems disagree about what a payment is, faster reporting only delivers the disagreement faster.
Reconcile from the bill to payroll
The IRS says an examiner may ask an employer to trace a transaction from the customer’s bill through the POS or sales journal and into payroll. That is also a strong monthly close control.
Start with this roll-forward:
Mandatory service charges added by the POS
less refunds and voids
equals net mandatory service charges collected
That net amount should then reconcile to:
amount retained by the restaurant
plus amount distributed as wages
Any difference needs an identified reason, owner, and resolution date.
Do the same for voluntary charged tips: trace the amount from the guest check to the card settlement, tips payable, payroll or payout record, and final clearing of the liability. This settlement-level discipline is also what reveals hidden leakage in delivery channels and other third-party payment flows.
Use a small sample of actual checks during the close. Include a normal table, a large-party auto-gratuity, a banquet or private event, a refunded check, and a check with both a mandatory charge and an additional voluntary tip. If the accounting team cannot explain the path without manual guesswork, the mapping is not finished.
Check the payroll consequences
Two consequences deserve special attention.
First, the IRS excludes distributed service charges from the FICA tip credit because they are non-tip wages. If a payroll or tax process includes those amounts in the credit calculation, the credit may be overstated.
Second, the U.S. Department of Labor says distributed service charges are not tips under the Fair Labor Standards Act and must be included in the employee’s regular rate of pay when computing overtime. A service-charge earning code that bypasses the regular-rate calculation can understate overtime.
These are not reasons to avoid service charges. They are reasons to configure them intentionally. The service model, employee communication, written policy, payroll code, and accounting treatment should all describe the same arrangement.
Run a year-end control review
Before final 2026 payroll, assign one owner to complete these checks:
- Inventory every mandatory charge used in dining, large parties, private events, catering, and online ordering.
- Capture the exact menu, contract, and checkout language that the guest sees.
- Confirm the POS code for each charge and whether the guest can choose zero.
- Verify the general-ledger destination for sales, service-charge income, service-charge wages, and tips payable.
- Verify the payroll earning codes for distributed service charges and reported tips.
- Confirm that service-charge wages enter the regular-rate calculation for overtime.
- Exclude service charges from reported-tip fields, Form 8027 tips, and the FICA tip-credit workpaper.
- Review the 2026 Form W-2 setup for code TP and box 14b with the payroll provider.
- Make the pay-stub description understandable to employees.
- Test at least five transactions from guest check to bank settlement to payroll and general ledger.
Keep the completed mapping and test results with the year-end payroll workpapers. The record is useful for tax reporting, but it also protects management time. When an employee, manager, payroll provider, or examiner asks what happened, the answer should be in the process—not buried in someone’s inbox.
Make the reporting useful to operators
Once the classifications are clean, the management report can answer better questions:
- How much of each service charge was retained, distributed, or used to cover administrative costs?
- What was the payroll-tax and overtime cost of the distribution policy?
- Did the policy change voluntary tip behavior or employee take-home pay?
- Are private events and large parties contributing the margin management expected after the full wage cost?
- Are managers using the same definitions across locations and shifts?
The point is not merely compliance. A mandatory charge is part of the restaurant’s pricing and labor model. Treating it as a distinct economic stream lets management see whether the policy is supporting the guest experience, the employee promise, and the business model.
If your restaurant, brewery, brewpub, or taproom cannot trace a service charge from the guest check through payroll and the general ledger, a Lord CPAs Financial Clarity Review can help identify the broken handoffs and turn them into a practical close process.
About Lord CPAs: Lord CPAs helps restaurants, breweries, brewpubs, and taprooms build financial systems that support clearer operating decisions. This article discusses general federal tax and wage principles; state and local rules vary, and operators should coordinate with their payroll provider, tax adviser, and employment counsel for their facts.
