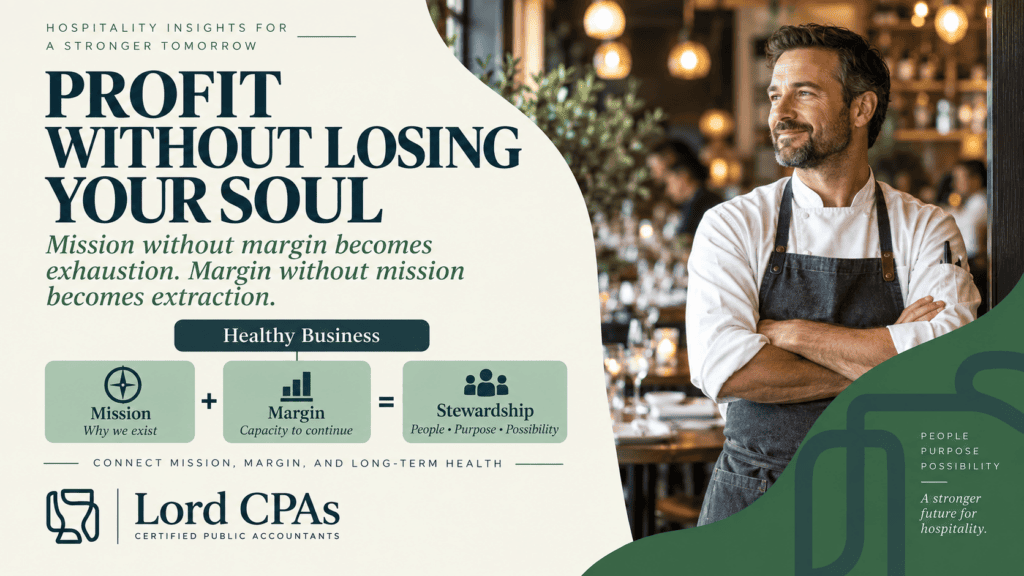
Mission without margin becomes exhaustion. Margin without mission becomes extraction. A healthy business needs both.
Throughout our From Financial Statements to Operating Decisions series, we have made one central argument:
The numbers on your financial statements are outcomes.
Revenue, cost of goods sold, labor, operating expenses, and ultimately profit are the accumulated result of operating decisions made throughout the business.
That is why the series ended by building a restaurant metric tree—tracing financial outcomes backward until we reached the operating drivers, behaviors, and decisions that people can actually influence.
But once you can see those connections clearly, another question emerges:
What are all of those decisions ultimately in service of?
It is tempting to answer: profit.
And profit absolutely matters.
A healthy business must generate enough economic value to survive, reinvest, reward ownership, withstand uncertainty, care for its people, and continue serving customers.
But profit alone is an incomplete definition of success.
A business can produce attractive financial results while slowly sacrificing the very things that made it worth building.
That is the tension.
Mission without margin eventually becomes exhaustion.
Margin without mission eventually becomes extraction.
The work of financial stewardship is learning how to hold both.
Profit Is Not Something to Apologize For
Especially in mission-driven businesses, conversations about profit sometimes become unnecessarily uncomfortable.
Owners may feel as though caring deeply about employees, customers, craft, hospitality, or community somehow conflicts with wanting a profitable company.
It does not.
Profit creates capacity.
It allows a restaurant to replace aging equipment instead of waiting for it to fail.
It creates room to train managers rather than throwing them into roles before they are ready.
It provides reserves for a slow season, equipment failure, economic downturn, or unexpected repair.
It supports wage growth, benefits, technology, better systems, and reinvestment.
And it allows owners to receive an appropriate return for the capital, time, and risk they have committed to the business.
Most importantly, profitability gives an organization the capacity to keep doing the work it exists to do.
A business that chronically loses money cannot indefinitely protect its employees, serve its guests, support its community, or fulfill its mission.
Eventually, someone absorbs the cost.
Sometimes it is the owner.
Sometimes it is employees through understaffing or inadequate compensation.
Sometimes it is vendors through stretched payment terms.
Sometimes it is customers through declining quality.
Sometimes it is the organization itself through deferred maintenance, underinvestment, or mounting debt.
This is why financial discipline is not opposed to mission.
Financial discipline protects mission.
But Profit Is Not the Purpose
The opposite mistake is just as dangerous.
Once profit becomes the sole definition of success, nearly every decision begins to look like an optimization problem.
Can labor be reduced?
Can purchasing costs go lower?
Can another position remain vacant?
Can maintenance wait another quarter?
Can managers absorb more responsibility?
Can product quality decline slightly without the customer noticing?
Some of those decisions may be entirely appropriate.
Every healthy business should improve productivity, eliminate waste, negotiate intelligently, and protect margin.
The problem begins when leadership asks only:
“Will this improve the number?”
instead of:
“Will this strengthen the business?”
Those are not always the same question.
A restaurant can improve labor percentage by consistently scheduling too few people.
It can reduce repairs expense by postponing maintenance.
It can improve food cost temporarily by compromising product quality.
It can improve short-term cash flow by delaying investment in equipment, training, systems, or management capacity.
The financial statements may look better.
The organization may actually be getting weaker.
That is why profit is an essential measure of organizational health—but never the only one.
The Soul of a Business Is Practical
Talking about the “soul” of a business can sound abstract.
It does not need to be.
The soul of a business lives in very practical questions:
Why does this organization exist?
What promise are we making to our customers?
How should people experience working here?
What are we unwilling to sacrifice merely to improve a financial result?
What kind of organization are we trying to build five or ten years from now?
For a restaurant, the answers may include hospitality, product quality, craftsmanship, consistency, employee development, community, or simply creating a place where people genuinely enjoy gathering.
For another business, the answers will be different.
What matters is that those values eventually reach the operating decisions.
Otherwise, they remain words on a website.
Your Financial Statements Reveal What You Actually Prioritize
One of the more uncomfortable truths about financial reporting is that the numbers often reveal more about an organization’s priorities than its stated values do.
Consider a company that says developing people is important.
Does the organization invest in training?
Are managers given enough capacity to coach employees?
Is turnover measured?
Are compensation decisions deliberate?
Has the business created enough margin to afford the development it says it values?
Or consider a restaurant that says product quality is central to its identity.
What happens when commodity costs increase?
Does management understand pricing, menu mix, purchasing, yield, and contribution margin well enough to respond intelligently?
Or does the organization simply pressure purchasing until quality begins to deteriorate?
Financial statements cannot tell you what your values should be.
But they can reveal whether your operating model is capable of supporting the values you say you have.
That makes financial analysis more than a performance-measurement exercise.
It becomes a form of organizational truth-telling.
Mission Can Also Become an Excuse
There is another side to this conversation.
Values can become an excuse for avoiding difficult economic decisions.
An owner may refuse to raise prices because they want to remain accessible.
A restaurant may continue operating an unprofitable daypart because regular customers enjoy it.
A company may maintain a staffing structure it can no longer afford because leadership cares about employees.
An organization may continue offering products or services that consume significant resources because eliminating them feels inconsistent with its history.
Those motivations may come from a good place.
But compassion without financial clarity can eventually create a much larger problem.
If the business continues weakening, the eventual decisions become more severe.
Instead of a modest price increase today, the company may require a dramatic increase later.
Instead of adjusting staffing gradually, leadership may eventually face layoffs.
Instead of closing an unproductive daypart, the entire location may become unsustainable.
Avoiding economic reality does not protect the mission.
It postpones the moment when reality must be confronted—usually at a higher cost.
Profit Can Be Borrowed From the Future
The reverse is also true.
Not every dollar of reported profit represents healthy economic performance.
Sometimes today’s margin is created by tomorrow’s problem.
Deferred maintenance is an obvious example.
Suppose a restaurant postpones necessary preventive maintenance to reduce expenses.
For a period of time, operating profit improves.
Nothing on the income statement labels that additional profit as borrowed from the future.
The statements simply show lower expense.
The same thing can happen with people.
A restaurant might operate with fewer managers than the business truly requires.
Payroll improves.
Managers absorb additional responsibilities.
Performance may remain stable for a while.
But underneath the financial result, exhaustion begins accumulating.
Eventually turnover increases, standards slip, training suffers, or a strong manager leaves.
Again, the original financial statements may have looked excellent.
The underlying organization was becoming weaker.
That is why stewardship requires a deeper question than whether profit increased:
How was the profit created?
Extraction and Stewardship Are Not the Same Thing
Extraction asks:
How much can we take out of this system?
Stewardship asks:
How do we keep this system healthy enough to continue creating value?
That does not mean owners should not receive distributions.
Quite the opposite.
Ownership deserves an appropriate return.
Capital has a cost.
Risk has a cost.
Entrepreneurial effort has a cost.
A business that requires owners to continually sacrifice their own financial well-being is not inherently more virtuous than one that produces strong returns.
But ownership is one legitimate claim on the economic value created by the business.
There are others:
Employees.
Vendors.
Taxes.
Debt service.
Equipment.
Technology.
Training.
Working capital.
Future investment.
Risk reserves.
And ownership.
Stewardship means intentionally balancing those competing claims rather than allowing whichever demand feels most urgent today to consume all available resources.
There is no universal formula.
But there should be a deliberate decision.
A Better Test of Profit
Instead of asking only:
“Did we make enough money?”
leaders can ask a broader set of questions.
Is the business economically durable?
Are we generating enough operating profit and cash flow to meet obligations, withstand normal volatility, and continue operating without recurring financial crisis?
Where did the margin come from?
Did profitability improve because waste declined, productivity increased, pricing improved, purchasing became smarter, or processes became more effective?
Or did it improve because necessary expenses were postponed?
Are we investing enough in the future?
Are equipment, systems, facilities, training, management capacity, and working capital keeping pace with the needs of the organization?
Are people becoming more productive—or simply more burdened?
Labor should absolutely be managed.
But improving labor productivity is different from requiring fewer people to carry an unsustainable workload indefinitely.
Are customers still receiving the value we promise?
If margin improves while quality, hospitality, service, reliability, or trust deteriorate, the financial improvement may not be sustainable.
Are owners receiving an appropriate return?
Healthy stewardship includes ownership.
A financially healthy business should ultimately reward the people who supplied capital, accepted risk, and built the organization.
Do we have enough capacity for something to go wrong?
A business with no liquidity, no reserves, no management capacity, and no operating flexibility may technically be profitable while remaining extremely fragile.
Together, these questions give us a more useful definition of financial health.
Financial Clarity Should Reduce Fear
This has been one of the recurring themes throughout From Financial Statements to Operating Decisions.
Good financial information should help people understand the business.
It should not simply give leadership another mechanism for assigning blame.
When food cost rises, the purpose of measurement is not to find someone to punish.
It is to understand whether the cause is purchasing, mix, waste, yield, portioning, pricing, inventory controls, or something else.
When labor increases, the question is not automatically:
“Who scheduled too many hours?”
It may be:
What happened to demand?
How productive were those hours?
Was staffing deployed correctly?
Was overtime necessary?
Was management compensating for an operational weakness somewhere else?
Financial clarity creates the possibility of discernment.
And discernment allows leaders to distinguish between a problem that requires correction and an investment worth making.
Because businesses do not become healthier simply by spending less.
They become healthier by allocating resources more intelligently.
The Numbers Need Something to Serve
The metric tree at the end of our series gave us a management system for connecting financial outcomes back to operating activity.
That system can tell us a great deal.
It can show us where margin is changing.
Where productivity is improving.
Where waste is occurring.
Where pricing needs attention.
Where operating practices are producing unexpected financial consequences.
But the metric tree cannot decide what the organization ultimately values.
Leadership must do that.
The numbers are extraordinarily useful servants. They are poor masters.
Their proper role is to help leadership see reality clearly enough to make responsible decisions.
Sometimes that means cutting an expense.
Sometimes it means increasing one.
Sometimes it means raising prices.
Sometimes it means investing in people.
Sometimes it means closing something.
Sometimes it means building something.
Sometimes it means accepting temporarily lower margin because the organization is intentionally investing in its future.
The financial statement records the outcome.
Stewardship determines what we do with the information.
A Healthy Business Needs Both Mission and Margin
There is no lasting virtue in running an organization into the ground for the sake of its mission.
And there is no lasting health in maximizing financial return while slowly hollowing out the organization that produces it.
The strongest businesses learn to hold both.
They generate enough profit to protect the enterprise.
They pay attention to cash.
They measure productivity.
They price intelligently.
They eliminate waste.
They reinvest deliberately.
They make difficult decisions when necessary.
They reward ownership.
They develop people.
And they remember why the business exists.
That combination is not a compromise between purpose and financial discipline.
It is what stewardship looks like.
Mission gives margin something worth serving.
Margin gives mission the capacity to continue.
A healthy organization needs both.
From Financial Clarity to Stewardship
The From Financial Statements to Operating Decisions series asked leaders to move beyond simply reading financial statements and begin understanding the operating decisions behind them.
This article asks the next question:
Once you understand what the numbers are telling you, what will you do with that clarity?
At Lord CPAs, we help restaurant and hospitality leaders understand what is happening beneath their financial results, identify the operating decisions that matter most, and build healthier businesses around that understanding.
Because the goal is not simply to improve the numbers.
The goal is to build an organization strong enough to:
serve customers well,
care for its people,
reward ownership,
invest in its future,
withstand uncertainty,
and continue doing meaningful work for years to come.
That is what financial stewardship is for.
